Boaseoruisnaesteigan
Perceived risk clarified
From one puzzling decision to a structured approach for understanding perceived financial risk in everyday choices
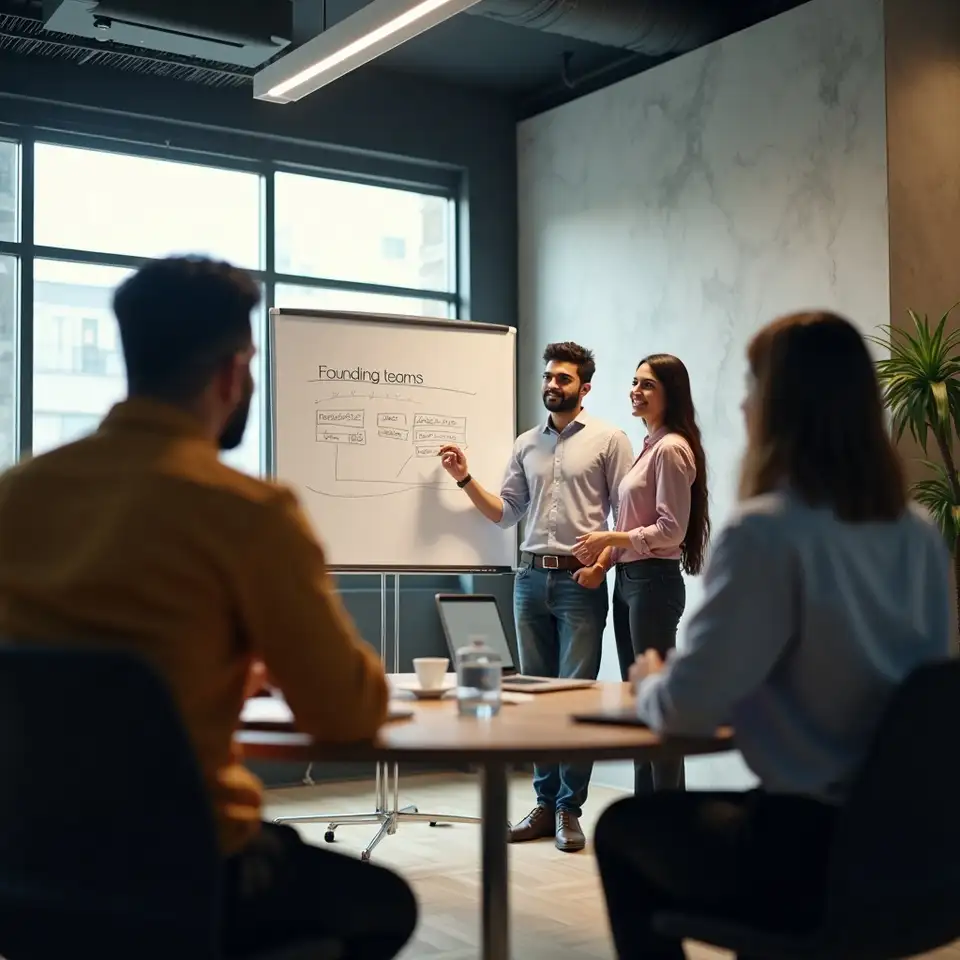
The project began when repeated client meetings revealed a pattern. Similar financial data. Very different reactions to the idea of changing a portfolio mix. The founding group combined backgrounds in finance, psychology, and data analysis to examine how perceived financial risk was formed. Early work focused on interviews, simple experiments, and careful review of existing behavioral research tailored to Indian conditions.
After the initial phase, the team created structured interview guides and survey instruments to measure subjective risk perception more consistently. Patterns emerged around past market experiences, family expectations, and news exposure. These findings shaped checklists that advisors and individuals could use before major financial decisions, making the hidden drivers of fear and comfort more visible.
The next milestone involved working with practitioners who advise budget conscious earners. Their real world cases tested whether the frameworks held up under pressure. Feedback led to simpler visual aids, clearer language, and more practical steps for discussing perceived financial risk without pushing any specific financial product or service.
Recently, the team has focused on refining methods and documenting a consistent approach. This includes a three step internal framework for reviewing perceived risk, checking emotional triggers, and aligning choices with realistic capacity to absorb loss. The work is updated for 2026 conditions in India, with ongoing monitoring of how news cycles and policy changes influence subjective risk levels.
Lead researcher and behavioral finance analyst
Behavioral risk perception consultant
Data and methodology lead
Client insight and practitioner liaison
Research operations and participant outreach
Visual frameworks and tool design
Compliance and ethical review
Insights translation and stakeholder reports
Each principle acts like a guardrail, keeping perceived financial risk analysis grounded in data, respectful of limits, and transparent about uncertainty for people in India.
Accessibility means that insights about perceived financial risk should be understandable without a background in advanced finance or psychology. Complex models are translated into clear language, concrete examples, and simple visuals that a budget conscious reader can relate to everyday decisions. Technical terms are minimized or explained in plain words. The goal is not to simplify reality beyond recognition, but to remove unnecessary barriers that keep people from engaging with their own attitudes toward risk. When a concept cannot be explained clearly, it is reworked until it can be or set aside until better tools exist. This respect for clarity helps individuals make more informed choices without feeling overwhelmed.
Ethics in financial guidance requires putting the individual’s risk tolerance, capacity, and situation ahead of any product push or personal preference. The project does not promote specific financial instruments or promise particular outcomes. Instead, it focuses on mapping how perceived risk is formed, where it may be distorted, and how that distortion might affect choices. Conflicts of interest are disclosed where relevant, and recommendations are framed as considerations, not instructions. The team avoids exaggerated claims about performance and includes reminders that past performance does not determine future results. This stance protects users from pressure and keeps the focus on informed, balanced decisions.
Transparency about uncertainty is central to any honest discussion of financial risk, perceived or measured. No model, checklist, or framework can fully predict future market behaviour or individual reactions. The team makes this clear in its materials and conversations. Scenarios are presented as possibilities, not promises. Language that implies certainty is avoided. Where data is incomplete, that gap is stated openly. Users are reminded that results may vary and that past performance does not guarantee future results. This openness may feel less comforting than bold claims, but it respects the reality of uncertainty and encourages more cautious, thoughtful decision making.
Recognition for early work highlighting how perceived financial risk can diverge sharply from measured volatility, helping advisors frame portfolio choices more responsibly for cautious clients.
Acknowledgement from a professional network in India for building accessible tools that explain subjective risk assessment without technical jargon while staying faithful to data.
Mention in a behavioral science community for collaboration across psychology and finance, focusing on how emotions, habits, and context shape responses to the same financial information.
Positive feedback from practitioners who used the team’s checklists and visual aids to open more balanced discussions around portfolio changes with budget conscious individuals.
Questions about how perceived financial risk is shaping decisions for a team, client base, or household are serious, not abstract. If a neutral, data informed view could help, a short conversation can clarify whether this project’s frameworks fit the situation. No pressure, only clear next steps.